Flexible payment plans are one of the main reasons buyers consider off-plan property in Dubai.
Rather than paying the full purchase price at once, buyers can spread instalments across reservations, construction, handovers, and, in some cases, the period after completion.
However, a low initial payment does not necessarily mean that a property is affordable over the full purchase journey.
The buyer must understand:
- How much is payable at booking
- How much is due during construction
- What remains outstanding at handover
- Whether mortgage finance will be required
- Whether payments continue after handover
- What happens if an instalment is missed
A suitable Dubai property payment plan is not simply the one with the smallest first payment. It is the structure that the buyer can manage comfortably through every stage.
How Off-Plan Payment Plans Work
An off-plan payment plan divides the property price into scheduled instalments.
These may be linked to:
- Contract signing
- Specific dates
- Construction milestones
- Handover
- A post-handover period
The exact structure is set out in the Sales and Purchase Agreement.
Dubai requires off-plan projects to be registered and linked to a dedicated project escrow account. DLD also requires the project payment plan as part of the escrow-account activation process.
Buyers should therefore compare the advertised payment plan with the formal SPA before signing.
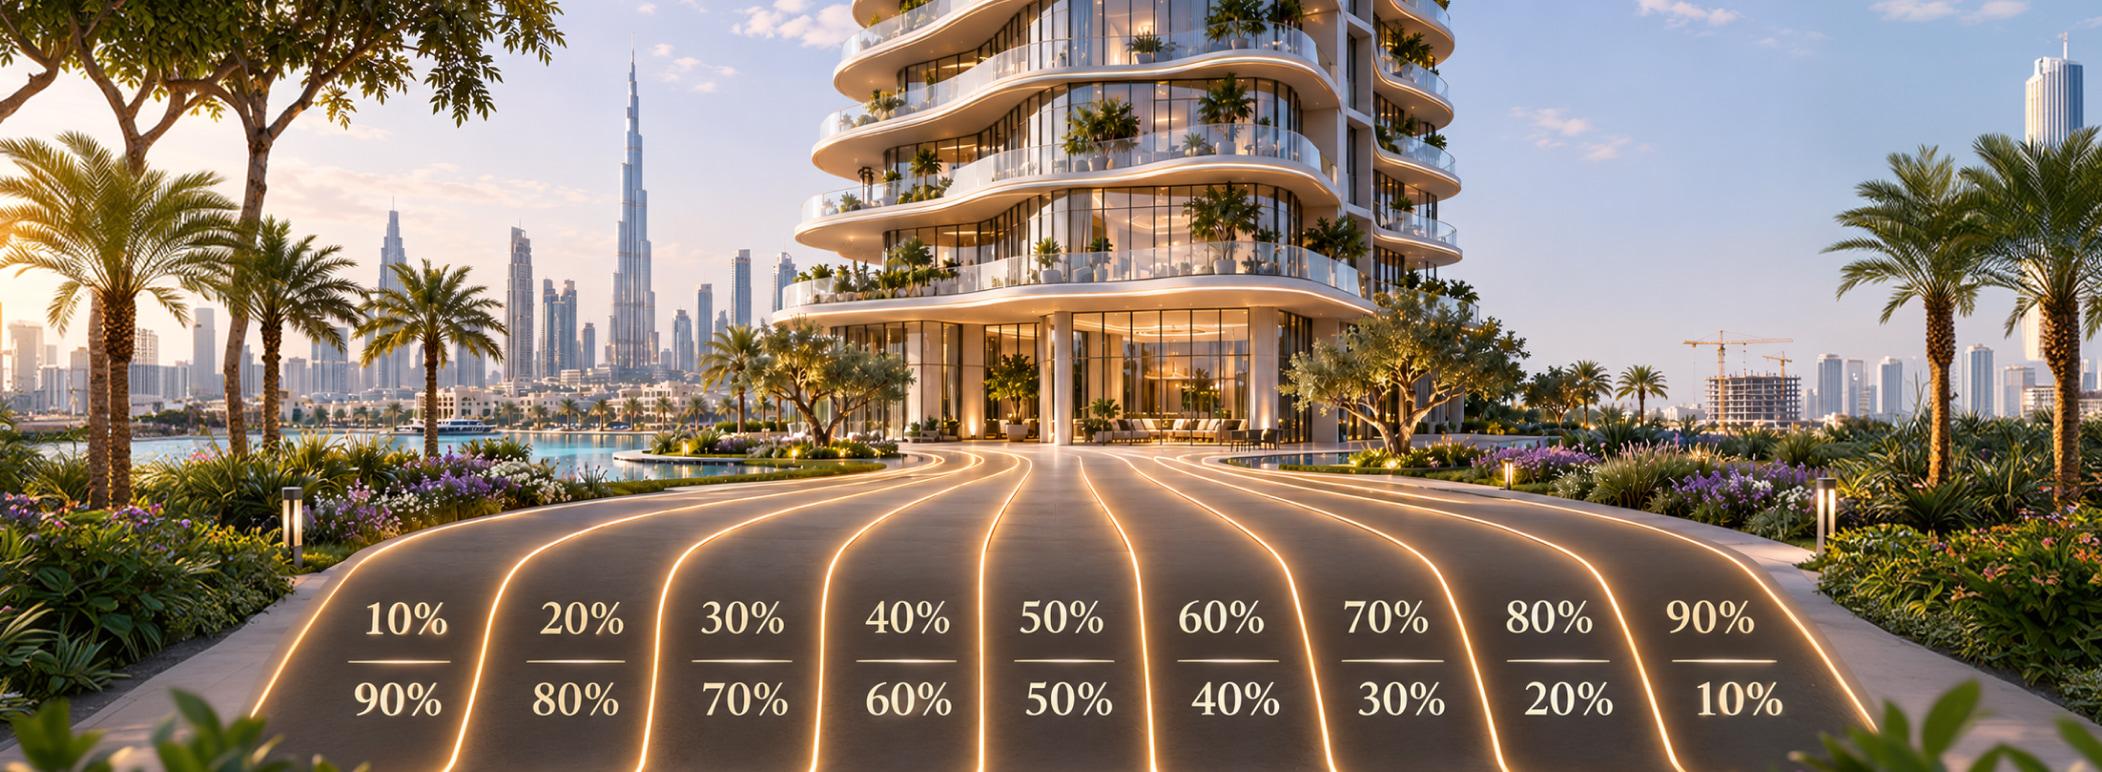
What Does a 20/80 Payment Plan Mean?
A 20/80 payment plan typically means:
- 20% is paid before handover, usually through booking and construction instalments
- 80% is paid at or near handover
This structure can reduce payments during construction but create a large final obligation.
It may suit buyers who:
- Expect to have substantial funds available at completion
- Plan to arrange a mortgage before handover
- Are selling another asset
- Prefer to preserve cash during construction
The main consideration is the size of the final payment.
A buyer should not assume that mortgage approval will automatically be available when the 80% becomes due.
What Does a 40/60 Payment Plan Mean?
A 40/60 payment plan generally divides the price into:
- 40% before handover
- 60% at handover or according to the final construction stages
This requires a larger proportion of the purchase price during construction than a 20/80 plan, while still leaving a significant final payment.
It may suit buyers who want:
- Moderate instalments during construction
- A lower handover balance than a 20/80 plan
- Time to prepare for financing or final settlement
The buyer should calculate whether the 60% payment remains manageable after accounting for registration, mortgage, furnishing, and move-in costs.
What Does a 50/50 Payment Plan Mean?
A 50/50 payment plan usually requires:
- 50% during reservation and construction
- 50% at or around handover
This divides the purchase price more evenly between the construction period and handover.
It may suit buyers who:
- Have reliable savings or income during construction
- Prefer a smaller final balance
- Want to reduce dependence on future financing
- Are comfortable committing more capital before completion
The trade-off is that more money is paid before the home is ready for occupation or rental.
What Is a Construction-Linked Payment Plan?
A construction-linked plan ties instalments to specified stages of project progress rather than only calendar dates.
Payments may become due when the project reaches milestones such as:
- Foundation completion
- Structural progress
- Façade installation
- Major construction stages
- Completion and handover
Dubai REST and DLD’s Project Status services allow buyers to review available project completion information and escrow details for registered developments. DLD’s Project Status Enquiry also provides official project completion information.
Buyers should compare every payment request with the SPA and the official project information available through DLD.
What Is a Post-Handover Payment Plan?
A post-handover payment plan allows part of the price to be paid after the property has been completed and handed over.
For example, the buyer may pay:
- A percentage during construction
- A percentage at handover
- The remaining balance through monthly or quarterly instalments after handover
Potential advantages include:
- Lower handover pressure
- Continued instalments after moving in
- The possibility of using rental income towards later payments where the property is leased and sufficient income is generated
- Reduced immediate dependence on a mortgage
However, post-handover plans require the buyer to continue meeting payment obligations after receiving the property.
Buyers should confirm:
- Length of the post-handover period
- Instalment frequency
- Whether interest or administrative fees apply
- Consequences of missed payments
- Whether title transfer is immediate or conditional
- Whether the property can be resold before full payment
Payment Plan vs Mortgage
A developer's payment plan and a mortgage are different.
A developer's payment plan is governed by the SPA and arranged directly with the developer.
A mortgage is finance provided by a bank and subject to:
- Income assessment
- Credit history
- Debt commitments
- Property valuation
- Loan-to-value limits
- Bank eligibility requirements
Under current CBUAE rules, the maximum loan-to-value ratio for a mortgage on an off-plan property is 50%, regardless of buyer category, property value or intended use.
A buyer should therefore avoid choosing a handover-heavy payment plan on the assumption that a bank will finance the entire remaining balance.
Booking Amount and Registration Costs
The initial booking amount is only one part of the upfront commitment.
Buyers may also need to budget for:
- DLD registration
- Administrative fees
- Mortgage-related costs
- Valuation
- Insurance
- Handover expenses
- Service charges
- Furnishing
DLD’s current initial-sale registration service lists a total registration charge of 4% of the sale value, divided as 2% for the seller and 2% for the purchaser under the service schedule. The SPA and project offer should confirm how those costs are allocated in the specific transaction.
Why the Escrow Account Matters
All amounts received from buyers of off-plan units must be deposited into the relevant project escrow account.
The account is opened in the project’s name and is dedicated to that development. Each project must have its own escrow account.
Before transferring an instalment, confirm:
- The project name
- Escrow-account details
- Beneficiary and escrow account details
- Payment reference
- Developer instructions
- Official receipt
Avoid transferring project instalments to a personal or unrelated account.
Oqood and Initial Sale Registration
Off-plan sales are recorded in Dubai’s provisional property register through Oqood.
DLD’s current service terms require the signed SPA to be registered within 90 days, after which the buyer receives an electronic provisional registration certificate.
Buyers should confirm:
- Who will register the sale
- When registration will take place
- Whether the fee has been paid
- When the certificate will be issued
- Whether the property and buyer details are correct
A reservation receipt does not replace Oqood registration.
How to Assess Whether a Payment Plan Is Affordable
Before choosing a property, map every instalment against expected income and savings.
Ask:
- What is payable today?
- What is payable during the next 12 months?
- Is there a large handover payment?
- Will a mortgage be required?
- Could I still pay if interest rates rise?
- Do I have funds for registration and handover costs?
- Can I manage the plan without depending on resale?
- What happens if my income changes?
A payment plan should remain affordable even if the property is not rented or resold immediately.
Payment-Plan Red Flags
Buyers should pause if they encounter:
- An unusually low booking amount followed by a large final payment that was not clearly disclosed
- Payment instructions that do not match the project escrow account
- Verbal promises not reflected in the SPA
- Unclear instalment dates
- A plan that depends entirely on future mortgage approval
- Penalties that have not been explained
- Pressure to pay before reviewing the contract
- A project that cannot be verified through DLD
- Assumptions that rental income will cover all instalments
The plan should be transparent from booking through final settlement.
Which Payment Plan Is Best?
There is no universally best structure.
A 20/80 plan may suit a buyer expecting significant funds later.
A 50/50 plan may suit someone who prefers a more balanced commitment.
A post-handover plan may support cash flow but extends the payment obligation after completion.
The right choice depends on:
- Income
- Savings
- Purchase objective
- Financing
- Risk tolerance
- Handover timeline
- Long-term ownership plan
Flexibility is valuable only when the full commitment remains manageable.
Conclusion
Off-plan payment plans in Dubai can spread the purchase price across construction, handover, and in some cases, the post-handover period.
However, buyers should evaluate the full schedule rather than focusing only on the booking amount.
Before signing, confirm:
- Every instalment
- Handover balance
- Mortgage requirements
- Escrow-account details
- Oqood registration
- Penalties and default terms
- Additional transaction costs
For Sobha Realty, payment flexibility sits alongside a wider commitment to construction quality, delivery and The Art of Detail.
A suitable payment plan should support the buyer’s ability to manage the purchase across each stage.
The developer’s delivery record, construction quality, and project transparency should be assessed separately from the payment structure itself.
Frequently Asked Questions
1. What does 20/80 mean in Dubai real estate?
It generally means 20% is paid before handover, and 80% is due at or near completion.
2. What is a post-handover payment plan?
It allows part of the property price to be paid after the completed home has been handed over.
3. Are off-plan buyer payments protected?
Buyer payments for registered off-plan units must be deposited into the project’s dedicated escrow account.
4. Can I use a mortgage for the handover payment?
Potentially, subject to bank approval and the applicable loan-to-value rules. Buyers should assess mortgage eligibility with a lender before relying on financing for a large handover payment.
5. How can I check off-plan project progress?
Use DLD’s Project Status Enquiry or Dubai REST to review available official completion and escrow information for the project.
6. When should an off-plan sale be registered in Oqood?
DLD’s current service terms require registration in the provisional register within 90 days of signing the SPA.
Explore Sobha Realty’s thoughtfully designed communities and discover flexible ownership opportunities supported by craftsmanship, construction visibility and long-term quality. Speak with a Sobha Realty advisor to review the payment structure that best aligns with your financial plans.